The bill comes fast.
Funeral homes usually want payment before the service. Your family has days, not months.
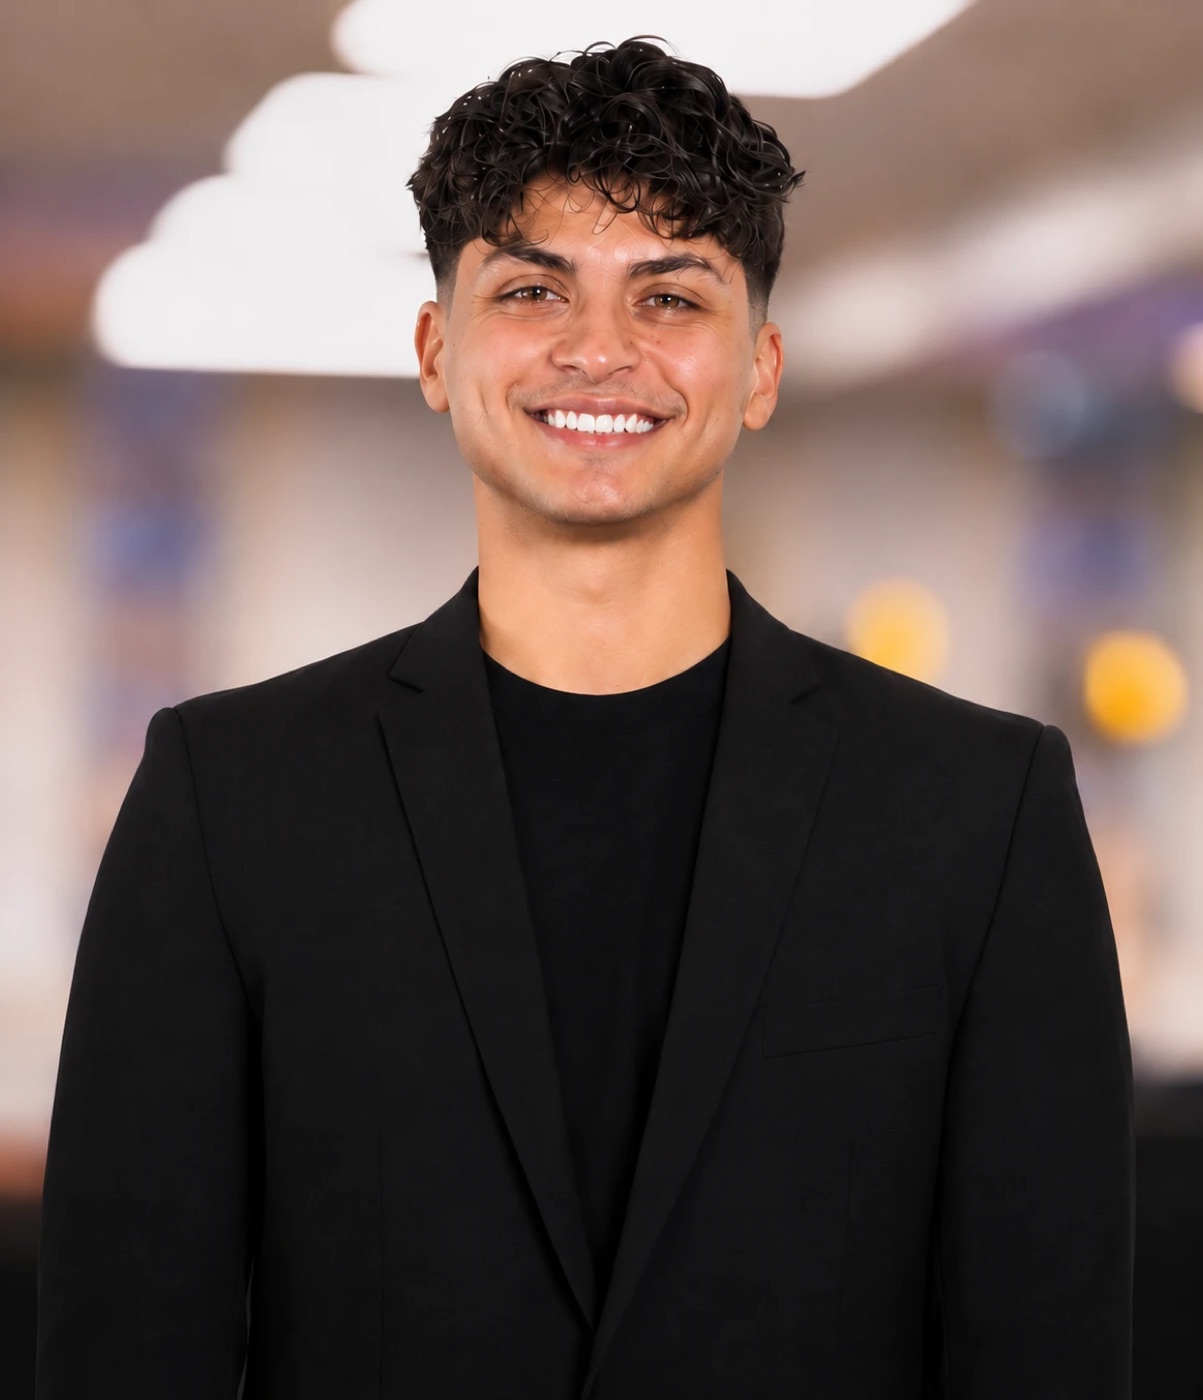
Final Expense Insurancewith Brandon Oliva, independent life insurance broker
Final expense is a smaller whole life policy that covers funeral costs and final bills, so your family doesn't have to. Often no medical exam.
A funeral costs more than most families have set aside. Here's what usually happens when there's no plan.
Funeral homes usually want payment before the service. Your family has days, not months.
Credit cards, savings, or a fundraiser, often while they're grieving and taking time off work.
Medical bills, a car payment, a credit card. Without a plan, it all lands on the people you leave behind.
Here's what you can check yourself before you ever talk to me.
Brandon Oliva, licensed life insurance agent, NPN 20227621. Search my name on the state's public licensee database.
Florida licensee searchAs an independent broker, I compare companies like Mutual of Omaha, Transamerica, National Life Group, and Aflac. Different carriers look at health differently.
I'm not connected to any funeral home. The money goes to your family, and they choose where to spend it.
Carrier names identify insurance companies we are appointed with. LIV INSURED. is not affiliated with or endorsed by them. Ratings refer to financial strength ratings from independent rating agencies and can change.
Three things every final expense plan should get right. This is how we build yours.
Burial or cremation, and the bills you'd leave
Coverage matched to what your family would actually need to pay.
Not a single funeral home
The money goes to the people you name. They choose the funeral home and what to pay first.
Whole life coverage
Coverage amounts are smaller than other life insurance. Some policies have a waiting period before the full benefit pays. Miss payments and the policy can lapse.
Have a list of your medications handy. It tells us which option you qualify for.
Options from 15+ A-rated carriers side by side, sized to your wishes and your budget.
Yes, no, or not yet. If you apply, many carriers give a decision quickly, and we stay with you after the policy starts.
Only one puts the full amount in your family's hands from the first day, no matter which funeral home they choose.
General descriptions. Pre-need contracts and account access rules vary by provider and state.
Which one you qualify for depends on a few health questions. Every option comes with the catch spelled out.
Full coverage from the first day if you qualify on health questions. Usually no medical exam.
See if I qualifyYou have to qualify on health questions. Coverage amounts are smaller than other life insurance, and the price per dollar of coverage is higher.
For people with certain health conditions who don't qualify for level benefit. Still no medical exam.
Ask about graded benefitIf you pass away from natural causes in the first two years or so, your family usually gets a partial benefit, not the full amount. It also costs more than level benefit.
You can't be turned down for health reasons, as long as you're within the age range.
Ask about guaranteed issueIt costs the most per dollar of coverage. There's usually a two to three year waiting period. If you pass away from natural causes during it, your family usually gets the premiums back plus interest, not the full benefit.
Every one gets the same treatment: what you've heard, why it's off, what's true, and how to check it yourself.
Why it's off. They will. But they'll be figuring it out in a few days, while grieving, with a bill due before the service.
What's true. A small policy means the money is there when they need it, and the decisions are already made.
How to check. Ask your family if they could pay for a funeral this week without borrowing.
Why it's off. Some advertised plans sell coverage in "units." The price looks small, but the dollar amount you get depends on your age.
What's true. Many of those plans also have a waiting period of two years or more. A low price can mean a small benefit.
How to check. Before you sign up for any plan, ask for the exact coverage amount in dollars and the length of the waiting period.
Why it's off. Final expense is built for older ages.
What's true. Many carriers offer it well into your 80s. The age range depends on the carrier and the type of policy.
How to check. Ask which carriers accept your age. That's why we compare 15+.
Why it's off. Different carriers look at health differently. A "no" from one isn't a "no" from all.
What's true. Many conditions still qualify for level or graded benefit. If not, guaranteed issue has no health questions, with a waiting period.
How to check. Bring your medication list to the consultation. We'll tell you which options fit.
Why it's off. Many people expect a large death benefit from Social Security.
What's true. Social Security may pay a one-time death payment of $255, and only to a spouse or some minor children. That's far less than a funeral costs.
How to check. See "Lump-sum death payment" on ssa.gov/survivor/amount.
Why it's off. Both plan ahead, but they work very differently.
What's true. A pre-need plan usually pays one funeral home for set services. Final expense pays your family in cash, and they choose.
How to check. Ask the funeral home what happens to the plan if you move or change your mind.
Why it's off. That's true for some types of insurance, not most final expense policies.
What's true. Most final expense whole life policies have a fixed price for life, and the coverage doesn't shrink.
How to check. Ask for it in writing: "Can my premium ever increase?"
Why it's off. Most final expense policies don't use exams.
What's true. They usually ask health questions instead. Guaranteed issue policies don't ask any health questions.
How to check. Ask before you apply: "Is there an exam, or just questions?"
If that's you, we'll tell you on the call. No pitch.
Use these with anyone, including us. If an agent can't answer them clearly, keep looking.
Ask exactly how long, and what your family gets if something happens during it. Level benefit policies usually have none.
Most final expense whole life policies have a fixed price for life. Get it in writing.
Some plans cut the benefit at a certain age. Ask for the coverage amount in dollars at every age.
It should be the people you choose, paid in cash, not a single funeral home.
Ask how long the grace period is and how to reinstate the policy. Setting up automatic payments helps.
What would you want for your service? Brandon reads your answer before the call, so your quotes are ready.
Free. No commitment. Coverage is subject to underwriting and carrier approval.
The rest of this page is real clients and families describing their experience. Read or watch as many as you like.
Client experiences are individual. They are not a promise or prediction of your results.