The payment is still due.
The bank expects the same payment next month, whether there's one income in the house or two.
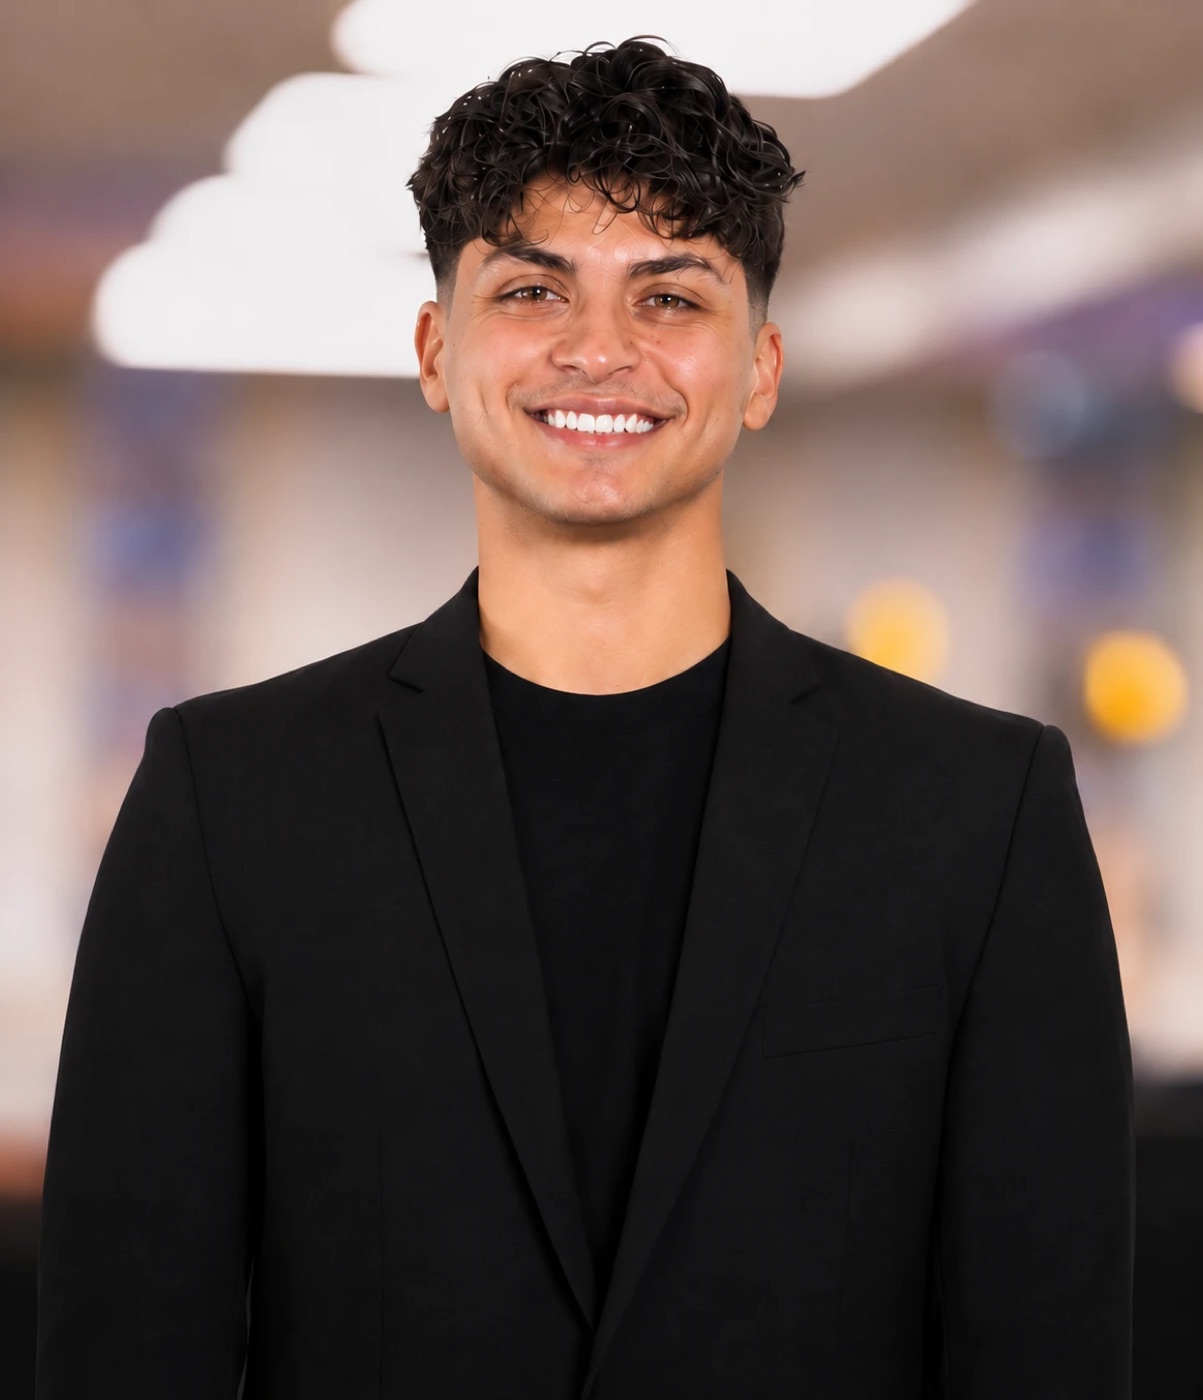
Mortgage Protectionwith Brandon Oliva, independent life insurance broker
Mortgage protection is life insurance sized to your mortgage. If something happens to you, the money goes to your family, not the bank.
Most families need one or two incomes to make the house payment. Here's what happens when one of them is gone.
The bank expects the same payment next month, whether there's one income in the house or two.
Drain savings, pick up more work, or sell the home, often while they're grieving.
PMI protects the lender, not your family. Lender life insurance usually pays the bank. More on that below.
Here's what you can check yourself before you ever talk to me.
Brandon Oliva, licensed life insurance agent, NPN 20227621. Search my name on the state's public licensee database.
Florida licensee searchAs an independent broker, I compare companies like Mutual of Omaha, Transamerica, National Life Group, and Aflac. Not one company's product.
I'm not connected to your bank, your loan servicer, or any government agency. I work for you, not the loan.
Carrier names identify insurance companies we are appointed with. LIV INSURED. is not affiliated with or endorsed by them. Ratings refer to financial strength ratings from independent rating agencies and can change.
Three things every mortgage protection plan should get right. This is how we build yours.
Your balance and the years left
Coverage sized to what's left on the house, for as long as you'll be paying it.
A policy you own
The money goes to the people you name. They decide whether to pay off the house or keep the payments going.
What happens if you outlive it
Term coverage ends when the term does. Return of premium costs more. Conversion rules and age limits vary by carrier.
Your balance, years left, and who depends on your income. Questions first.
Options from 15+ A-rated carriers side by side, sized to your loan and your budget.
Yes, no, or not yet. If you apply, we guide you through underwriting and stay with you after the policy starts.
Three things get called mortgage insurance. Only one of them pays your family.
General descriptions. Terms of lender products and PMI vary by lender and loan.
Every option comes with the catch spelled out.
Coverage for the amount and length of your loan, like 20 or 30 years. The simplest way to protect the house.
Get my optionsCoverage ends when the term ends. If you still need coverage later, a new policy will cost more because you'll be older.
A term policy with an option that pays back the premiums you paid if you're still alive at the end of the term.
Ask about return of premiumIt costs noticeably more than plain term. If you cancel early, you may get back little or nothing. Not every carrier or state offers it.
Whole life or indexed universal life (IUL). Protects the house and keeps covering your family after the mortgage is gone.
See how IUL worksIt costs more than term for the same coverage. Cash value takes years to build, and loans charge interest.
Every one gets the same treatment: what you've heard, why it's off, what's true, and how to check it yourself.
Why it's off. PMI sounds like it protects you. It protects the lender if the loan defaults.
What's true. PMI isn't life insurance. If you pass away, it pays nothing to your family. Mortgage protection is a separate policy you own.
How to check. Look at your closing documents or call your servicer and ask, "Who does my PMI pay?"
Why it's off. Lender coverage is convenient, but it's built around the loan, not your family.
What's true. It usually pays the lender, often shrinks as your balance goes down, and usually ends if you refinance or move. A policy you own pays your family and goes with you.
How to check. Ask who the beneficiary is, whether the coverage decreases, and what happens if you refinance.
Why it's off. After you buy a home, your name and loan amount become public record. That's why official-looking letters show up.
What's true. They usually come from insurance marketers, not your lender or the government. You don't have to answer them. Coverage is your choice.
How to check. Call your lender using the number on your statement, not the letter, and ask if they sent it.
Why it's off. Work coverage is a nice perk, but it isn't yours.
What's true. It's often one or two times your salary, and it usually ends when you leave the job. Compare that number to your mortgage balance.
How to check. Ask HR for your coverage amount and what happens to it if you leave.
Why it's off. Later usually means older, and your health can change.
What's true. Price depends on your age and health when you apply. Covering the house now can lock in a price for the whole term.
How to check. Get a quote today and compare it to one five years from now. We'll show you both.
Why it's off. You paid for your family to keep the house if something happened. That protection was real every month.
What's true. If getting money back matters to you, return of premium is an option. It costs more, and canceling early can mean getting little or nothing back.
How to check. Compare a plain term quote and a return of premium quote side by side.
Why it's off. The name makes it sound that way.
What's true. The benefit goes to the people you name. They can pay off the house, keep making payments, or use it for other needs.
How to check. Look at the beneficiary section on the application. It's your choice.
Why it's off. Not every policy needs an exam.
What's true. Some carriers use health questions only. Others ask for an exam, often in exchange for a lower price. Approval depends on underwriting, and different carriers look at health differently.
How to check. Ask which carriers fit your health before you apply. That's why we compare 15+.
If that's you, we'll tell you on the call. No pitch.
Use these with anyone, including us. If an agent can't answer them clearly, keep looking.
It should be the people you choose, not the lender. Ask to see the beneficiary on the application.
Some policies shrink with your loan. A level policy stays the same, so your family gets more as the balance drops.
A policy you own stays with you. Coverage tied to the loan usually ends with it.
Ask whether you can convert to permanent coverage without a new medical exam, and until what age.
Many policies let you use part of the benefit early for a serious illness. Ask which illnesses count and how much it lowers the death benefit.
How many years are left on your mortgage? Brandon reads your answer before the call, so your quotes are ready.
Free. No commitment. Coverage is subject to underwriting and carrier approval.
The rest of this page is real homeowners describing their experience. Read or watch as many as you like.
Client experiences are individual. They are not a promise or prediction of your results.